What OpenAI Announced on 13 November: The Arrival of ChatGPT Wallet
On November 13, OpenAI revealed a flagship update to its AI ecosystem: the launch of ChatGPT Wallet, a payment gateway integrated directly into the ChatGPT platform. This move marks OpenAI’s shift from a pure conversational AI company toward more transactional, commerce-centric AI services. The core premise allows ChatGPT users—specifically those participating in the US trial—to empower their AI agents to make purchases on their behalf, with explicit purchase approval and robust payment controls.
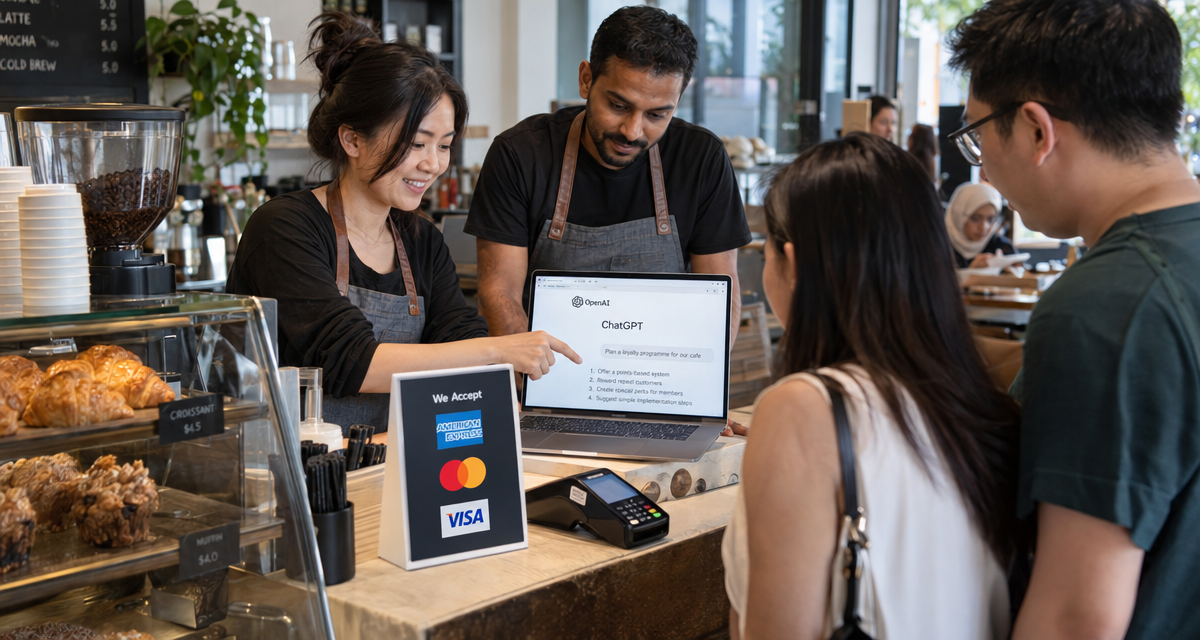
This announcement has immediate implications for merchants, payment processors, and integration partners. Technically, the ChatGPT Wallet is not a standalone “wallet” in the classic sense (like Apple Pay or Google Wallet) but rather a secure payment interface that authorizes agent-initiated purchases on e-commerce sites. The wallet supports credit card rails, with initial partnerships for purchase processing via Visa, Mastercard, and American Express.
- Key technical differentiators: rather than letting AI agents transact independently, all payments pass through a human verification step. The agent can select products, fill the cart, and begin checkout—but the user must review the transaction through the ChatGPT interface before it is authorized and sent to the merchant.
- Merchant implications: e-commerce platforms must adapt their payment flows to recognize ChatGPT Wallet transactions, potentially requiring new fraud checks, integration points, and reconciliation logic. There are also questions around liability for unapproved or failed purchases.
- API and infrastructure impact: Current integrations primarily leverage standard card rails. Merchants with custom checkouts or non-standard fraud protection mechanisms may need to make adjustments or contact OpenAI for custom onboarding options.
This is not a mere checkout plugin—it’s the foundation for autonomous commerce, where agent-driven transactions must be balanced by user oversight, merchant adaptability, and payment ecosystem compliance.
How Shoppers Approve Agent Purchases: Controls, UX, and Security
The real innovation behind ChatGPT Wallet is the multi-stage approval flow that shifts the traditional consumer purchase path. When a user tasks their agent (“Find me the best noise-cancelling headphones and order them”), the AI can identify suitable products, add items to the cart, and prepare the checkout. But the agent cannot finalize the purchase:
- Once the agent configures the order, the user receives a detailed purchase prompt in their ChatGPT interface (desktop or mobile).
- The prompt outlines items selected, pricing, merchant name, shipping estimates, and payment method selection.
- The user must confirm or modify details. Only after explicit approval does the transaction proceed via the ChatGPT Wallet infrastructure on supported card rails.
Security and fraud concerns are addressed by this extra authorization step. OpenAI claims minimal card data is handled directly by the agent, and all sensitive actions require end-user involvement. However, as transactions scale, concerns arise:
- Phishing and social engineering: OpenAI’s UX must make clear which purchases genuinely originate from the user’s query versus those proposed by potentially manipulated agent interactions.
- False approvals and mistakes: The increased convenience of agent-driven shopping could lead to “approve-by-habit” behaviors. Merchants may face higher cancellation or refund rates if users do not carefully review agent proposals.
- Card-off-file and recurring payments: At launch, ChatGPT Wallet does not support subscriptions, but merchant roadmaps should consider how agent-led renewals could complicate PCI compliance downstream.
From a technical friction standpoint, the human-in-the-loop design is essential for regulatory compliance and consumer confidence. But it also introduces delays and possible drop-off in the checkout process, affecting conversion rates and post-sale support workloads for merchants.
What Merchants Receive at Checkout: Operational and Data Flow Considerations
For online merchants, the integration of ChatGPT Wallet introduces new checkout touchpoints and backend implications. Unlike mainstream wallet solutions that keep merchants largely abstracted from the consumer’s personal data, ChatGPT Wallet initially processes transactions by passing user and order details through OpenAI’s infrastructure before relaying them to the merchant’s e-commerce platform.
- Order flow: After user approval, the order is transmitted with all standard billing, shipping, and payment details. Merchants receive transactions as if completed by a highly-automated guest checkout—potentially from new, AI-recommended customers.
- Payment processing: Initial card payments appear as standard transactions via Visa, Mastercard, or American Express. Merchants will need to distinguish ChatGPT Wallet orders for reporting, analytics, and support, especially if disputes or fraudulent orders arise.
- User data granularity: Merchants may receive less direct shopping intent data, since product research and basket-building happened on the ChatGPT platform rather than on their own site—potentially impacting retargeting and CRM initiatives.
This model raises several technical dependencies:
- Integration requirements: Merchants on mainstream platforms (e.g., Shopify, Magento, BigCommerce) may see rapid enablement through plugins or backend schema updates. Those with bespoke carts will need to design custom endpoints and verify how ChatGPT Wallet tokens are recognized.
- Refund, dispute, and reconciliation: Since ChatGPT is in the transaction chain, customer service teams may receive new edge-case inquiries (“My agent ordered the wrong item—what now?”). Merchants must clarify refund and dispute processes in the context of agent-driven purchases.
The following comparison table breaks down how ChatGPT Wallet integrations compare to established wallet and card flows:
| Checkout Method | User Approval Step | Merchant Receives | Integration Complexity | Payment Rails | Ideal Merchant Size | Data Visibility |
|---|---|---|---|---|---|---|
| ChatGPT Wallet | Mandatory, in-app confirmation | Order + user details via AI agent | Moderate (API/plugin required) | Visa, Mastercard, Amex | SMB to Enterprise | Limited (AI pre-filters shopping intent) |
| Apple Pay / Google Wallet | On-device, biometric | Standard order + device token | Low (integrated by platform) | Card networks, occasionally bank rails | Micro to Enterprise | Standard web/mobile data |
| Direct Card Entry | User-typed, at checkout | Full customer and payment details | Low (native e-comm) | Visa, Mastercard, Amex | Micro to Enterprise | Full |
For merchants, the influx of agent-driven transactions may force substantial operational retooling. Marketing, order tracking, and customer support systems must evolve to handle transactions in which the user may not have direct web-session history with the store.
Which Users Can Access the Initial US Rollout: Eligibility, Limitations, and Access Barriers
At launch, ChatGPT Wallet access is tightly limited to a subset of US-based users with full KYC (know your customer) compliance and current ChatGPT Plus or Teams subscriptions. OpenAI’s decision to restrict the rollout is a calculated response to technical, regulatory, and support burdens scaling autonomous commerce can introduce.
- Eligibility: Only registered users with verified US addresses, holding a valid US-issued Visa, Mastercard, or American Express, can activate the wallet functionality. This leaves out most non-US customers and US residents without access to mainstream credit infrastructure.
- Platform limitations: The feature set is currently restricted to desktop and iOS; Android rollouts and API-based agent commerce are forthcoming but not yet available.
- Regulatory boundaries: By focusing on US customers, OpenAI sidesteps early complexities like GDPR data handling, cross-border tax, and global chargeback regimes—though these hurdles will eventually require attention.
For enterprise or high-traffic merchants, this focused US-only trial means the immediate user bump may be marginal, but infrastructure should be future-proofed for upcoming globalized support. Businesses relying heavily on international customers will need to track planned expansion updates from OpenAI.
- Operational tip: Merchants should segment sales originating from ChatGPT Wallet to monitor the demographic and payment source—in-house order processing tools may need to be adapted to distinguish these flows as the feature expands.
What Singapore Merchants Can Take From the Launch: Roadmap, Preparation, and Lessons
While Singapore and other non-US markets are not included in the initial ChatGPT Wallet release, merchants in Asia should interpret this rollout as a preview for how agent-driven payments—and the required ecosystem adaptations—will play out globally. There are several instructive takeaways and preparation opportunities:
- E-commerce stack readiness: Merchants relying on regional payment gateways or e-wallets should initiate conversations with platform vendors to understand timelines for ChatGPT integration. Local regulatory nuances (e.g., PDPA compliance, cross-border transaction tax) will require additional legal review.
- AI commerce risk management: Fraud controls, AI interaction monitoring, and abnormal purchase pattern detection become more complex when customer agents are making (or recommending) the purchase. Merchants should audit their anti-fraud systems for AI agent signal compatibility.
- Customer support and refunds: Expect increased support requests around agent-driven errors (“My agent misunderstood my request”). Prepare templated responses, clear return/refund policies, and identify chatbot escalation paths for such cases.
- Competitive benchmarking: Early adopters may gain advantages in AI commerce readiness, loyalty marketing, and dynamic re-pricing strategies as agents begin to shop across borders.
Singapore merchants, especially those selling regionally or to US expats, should monitor this rollout carefully. Collaboration with fintech partners will be critical to adapt for payment reconciliation, localized compliance, and CX design that anticipates agent-initiated purchases.
What to Watch Before Wider Availability: Future Roadblocks and Merchant Readiness
As OpenAI prepares for a broader ChatGPT Wallet deployment, several technical, operational, and policy-driven questions remain unsolved—each with potential knock-on effects for merchants worldwide.
- API and plugin standardization: Will OpenAI provide universal plugins for all major e-commerce platforms, or will bespoke integrations dominate the market? The answer will dictate onboarding speed and cost, especially for mid-sized businesses.
- Dispute mediation and liability: Without established industry protocols for agent-originated transactions, how will responsibility be split between OpenAI, payment processors, and merchants in cases of fraud, mistaken orders, or technical outages?
- Data feedback to merchants: Will AI workflows anonymize or shield upstream shopping insights from merchants, limiting their ability to personalize and upsell shoppers whose first point of contact was via ChatGPT?
- Infrastructure scaling and latency: As agent commerce grows, can OpenAI handle surge transaction volume and ensure that merchant sites do not suffer degraded performance or loss of analytics “session stickiness”?
- International and multi-currency support: Non-USD merchants should prepare for the complexity of adapting checkout flows and currency reconciliation to AI-mediated cross-border commerce.
Finally, merchants must remember that regulatory interpretations of agent-initiated AI payments are still evolving. PCI DSS implications, KYC responsibility, and customer consent frameworks will need continuous monitoring. Prudent organizations should dedicate resources for ongoing compliance and technical integration adjustments as the ChatGPT Wallet ecosystem matures.